Skanska’s Summer 2026 Construction Market Trends Report finds that U.S. construction demand remains stronger than anticipated, but growth is concentrated in sectors including data centers, infrastructure, power generation, advanced manufacturing, pharmaceutical production and select health care markets.
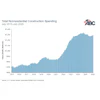
Data center construction continues to drive a significant share of growth. Data centers accounted for about 5.4% of private nonresidential construction spending in 2025, up from 1.7% in 2019. Annual U.S. data center construction spending is expected to surpass $100 billion by 2030.
At the same time, labor availability, power constraints and long equipment and material lead times continue to affect project delivery. Structural steel lead times can reach 40 to 50 weeks in some markets, while HVAC equipment lead times can extend to 52 weeks.
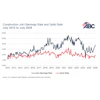
Construction costs also remain elevated in high-demand markets. Generator prices are expected to increase 8% to 10% in 2026, while HVAC equipment prices could rise 10% to 12%, according to the report.
The report also points to continued uncertainty surrounding tariffs and geopolitical conditions affecting steel, copper, aluminum, lumber and other construction materials.
With capacity constraints expected to remain a challenge, the report emphasizes early planning and procurement for long-lead materials and equipment. Meanwhile, office, retail, higher education and other commercial sectors continue to see comparatively subdued activity.